The HSA Triple Tax Advantage: The Only Account in America That Does This
The HSA is the only account in America with a triple tax advantage. Here's how it works, why most self-employed professionals aren't using it, and how to get started.

The HSA Triple Tax Advantage: The Only Account in America That Does This
The HSA is the only account in America with a triple tax advantage. Here's how it works, why most self-employed professionals aren't using it, and how to get started before you leave another tax deduction on the table.
The Triple Tax Advantage
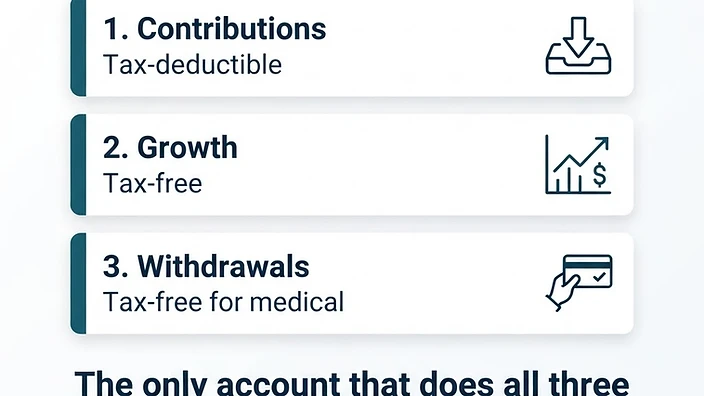
Every other tax-advantaged account in America gives you two out of three. The HSA gives you all three:
- Contributions are tax-deductible. Every dollar you put in reduces your taxable income for the year.
- Growth is tax-free. Invest your HSA balance, and the gains compound with zero tax drag.
- Withdrawals are tax-free for qualified medical expenses. Pull money out at any time for medical costs — no income tax, no penalty.
No other account does this. A 401(k) gives you tax-deferred growth but taxes the withdrawals. A Roth IRA gives you tax-free withdrawals but no up-front deduction. The HSA gives you the deduction and the tax-free growth and the tax-free withdrawal — as long as the money goes to medical expenses.
The Stealth Retirement Account
Here's the part most people miss: after age 65, HSA funds can be used for non-medical expenses penalty-free. You'll owe ordinary income tax on non-medical withdrawals, just like a traditional 401(k) — but if you use them for medical costs (and in retirement, you will), the withdrawal is tax-free too.
That makes the HSA three accounts in one:
- A health emergency fund — liquid cash for unexpected medical costs.
- A tax-advantaged investment account — grow the balance tax-free over decades.
- A stealth retirement account — penalty-free access after 65, tax-free for medical.
2026 Contribution Limits
For 2026:
- Individual: $4,400
- Family: $8,350
- Catch-up (55+): an additional $1,000
That's $4,400 per year you can deduct, invest, and withdraw tax-free for medical — or roll forward for retirement.
Why Most Self-Employed Professionals Aren't Using It
The catch: you can only contribute to an HSA if you're enrolled in an HSA-eligible High Deductible Health Plan (HDHP). And here's where most independent professionals get stuck — many popular ACA plans don't qualify. The plan that looks cheapest on the marketplace often disqualifies you from the account that would have saved you the most.
This is the number-one reason people miss the HSA: they pick a plan first, then discover it doesn't qualify. The right order is the reverse — decide you want the HSA, then choose a plan that qualifies.
The Investment Angle
Fund the HSA to the max and invest the excess, and the math gets serious:
- $4,400/year at 7% for 20 years ≈ $193,000.
That's nearly $105,000 in growth — tax-free — on top of $88,000 in deductible contributions. And if you use it for medical in retirement, the entire balance comes out tax-free. No other account in America compounds this way.
How to Get Started
- Get an HSA-eligible HDHP. Confirm the plan qualifies before you enroll — not after.
- Open an HSA. Many brokers offer investment options once you pass a small cash threshold.
- Fund it to the max. $4,400 individual / $8,350 family for 2026.
- Invest the excess. Keep a cash buffer for near-term medical costs; invest the rest.
- Save your receipts. You can reimburse yourself decades later for today's medical expenses — tax-free — as long as you keep the receipts.
The HSA is the only account in America that does this. If your plan doesn't qualify, you're leaving a triple tax advantage on the table every single year.
Not sure if your plan qualifies you for an HSA? Start at coveredbykeith.com — we'll check your plan's HSA eligibility and show you the true annual cost of the account you're missing.
Ready to explore your options?
Book a complimentary strategy call to discuss your health coverage needs.
Book a Complimentary Strategy CallNo obligation. This first conversation is simply a chance to understand your situation and determine whether it makes sense to explore further.
You'll be taken to our secure scheduling/contact page.